There’s a cheaper loanwith your name on it.
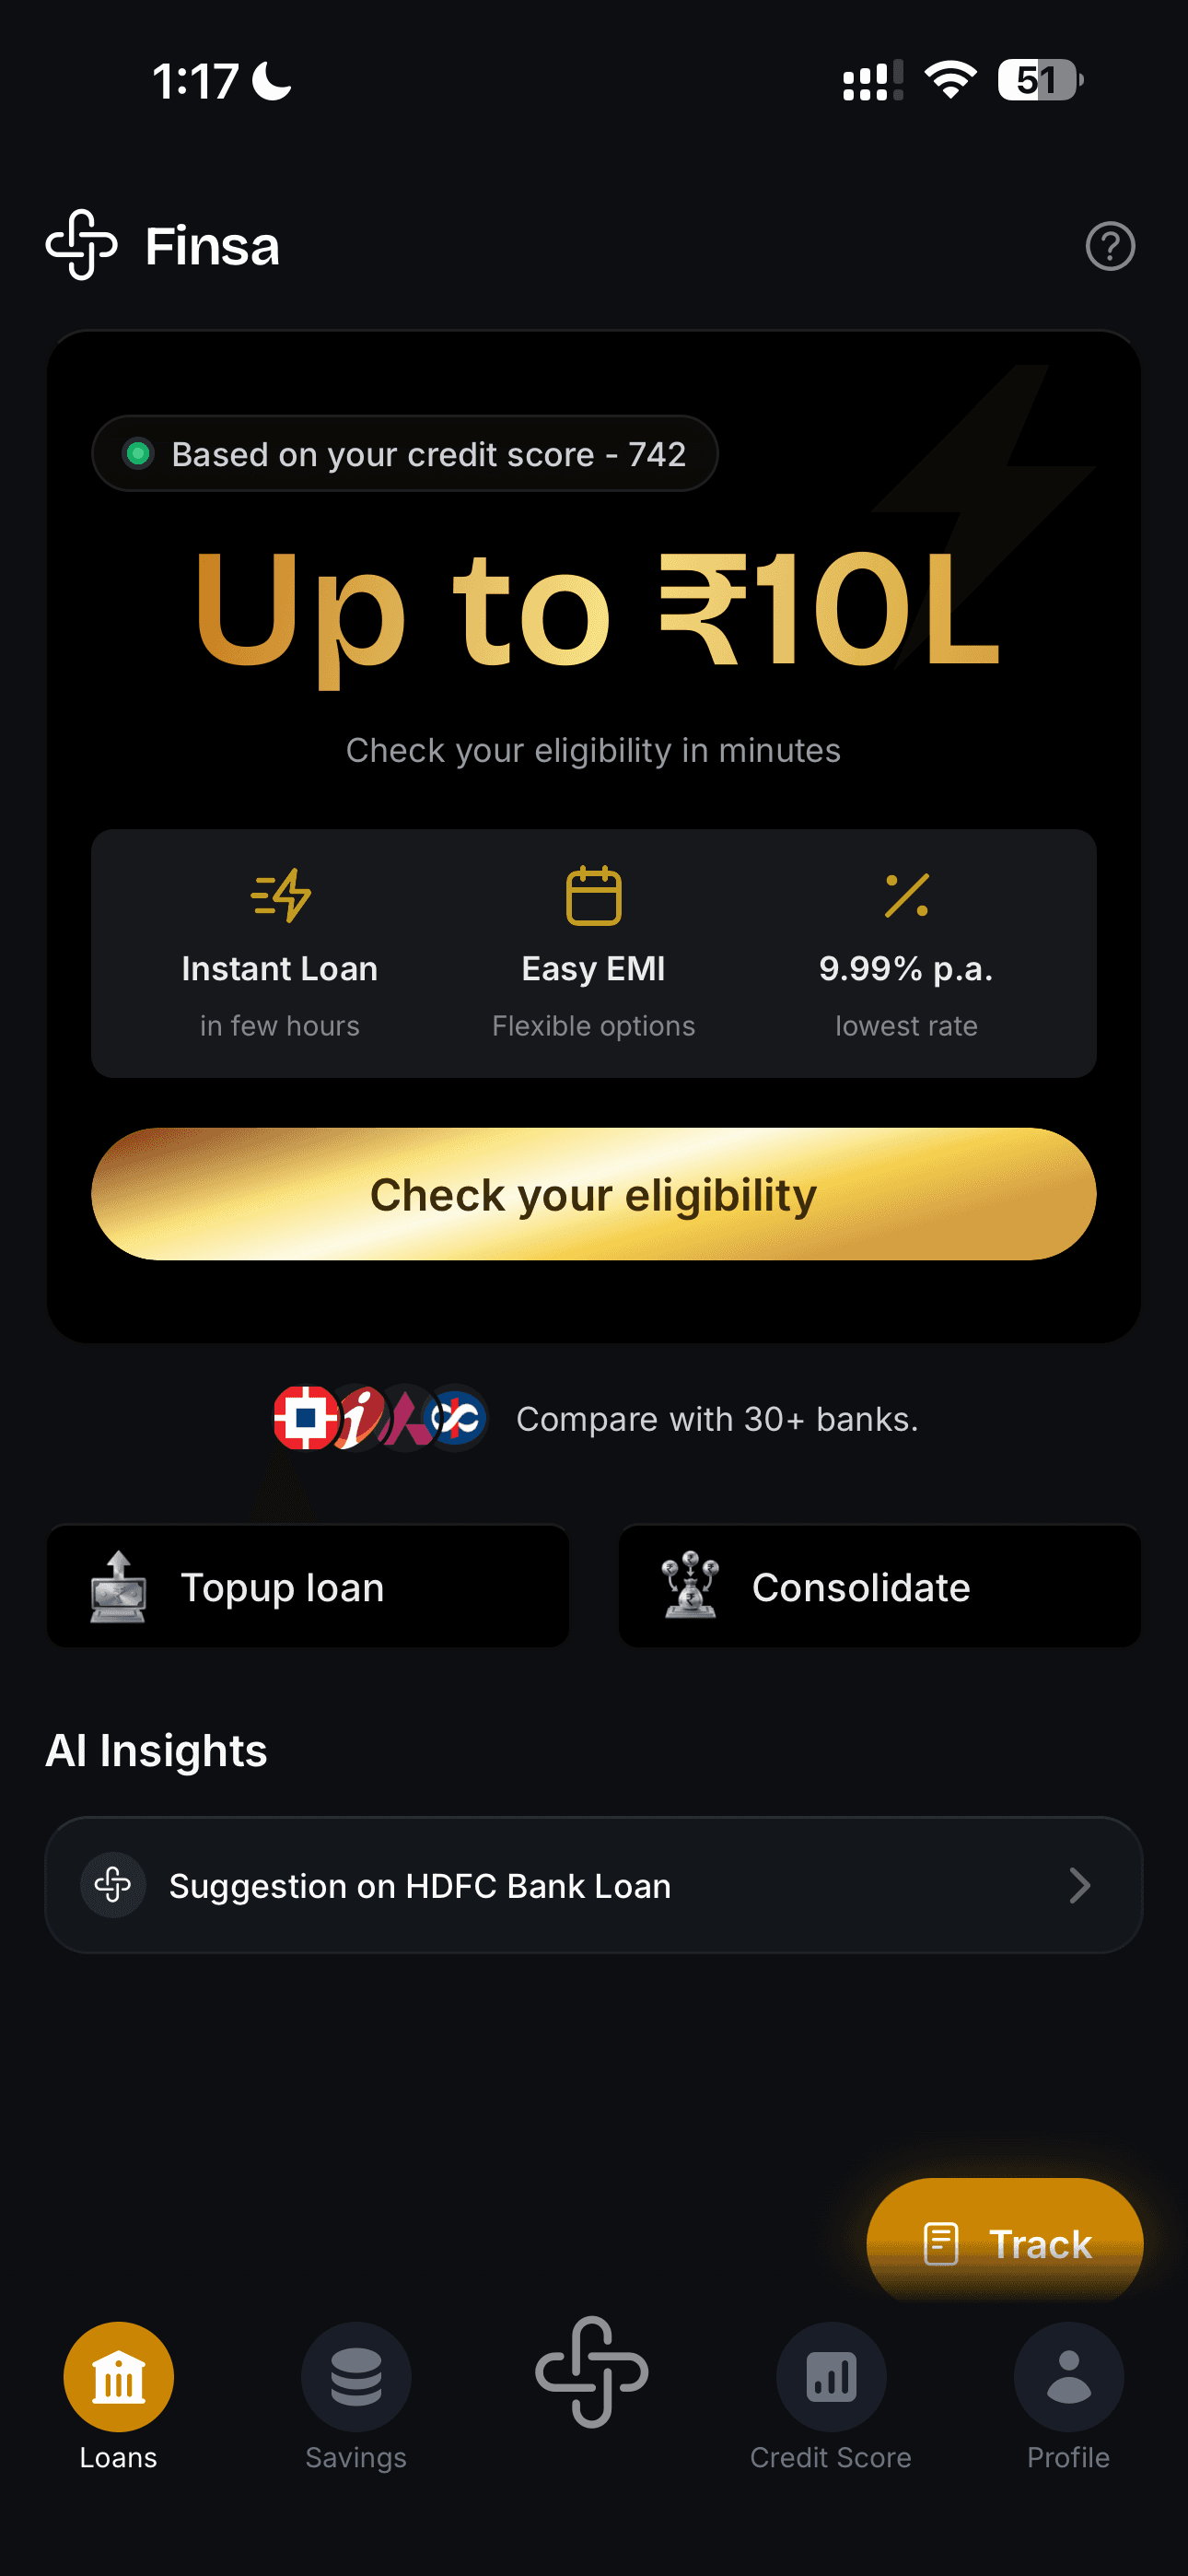
Check your Equifax report free. Finsa finds the loan quietly overcharging you and puts it in front of our lender partners — they send the offers, you pick. Checking never touches your score.


 RBI-regulated lending partners
In short
Finsa is a free Equifax credit-report check and a loan matchmaker from Finsamudra Private Limited, Bengaluru. One soft check, then RBI-regulated banks and NBFCs send offers for a new personal loan, a top-up, or one loan that replaces several EMIs, each with its rate, EMI and every fee on the lender's Key Fact Statement; you compare on APR and pick, and the lender pays into your bank account. Finsa is a Lending Service Provider. We don't lend — our RBI-regulated partners do. Finsa charges no processing fee and no fee of any kind, and is paid by the lender on disbursal. Checking never affects your score.
Finsa is built on the borrower's side: lenders compete for you, you see every matching offer, you pay Finsa nothing, and your data is yours to delete.
RBI-regulated banks & NBFCs on the panel. Finsa is a Lending Service Provider. We don't lend — our RBI-regulated partners do.
A selection of our lending partners
 HDFC Bank
 ICICI Bank
 IDFC First Bank
 Axis Bank
 Kotak Mahindra
 Bajaj Finserv
 Tata Capital
 SBI
 IndusInd Bank
 Yes Bank
 Federal Bank
 RBL Bank
 Bandhan Bank
 AU Small Finance
 Bank of Baroda
 Canara Bank
 Punjab National Bank
 Union Bank
 Indian Bank
 Karnataka Bank
 Karur Vysya Bank
 Citi
 Standard Chartered
 Muthoot Finance
 Capital Float
Three ways to borrow
Whichever you need, the same deal: one check, several lenders, no fee from Finsa.
- Personal loanA new personal loanOne soft check, offers from several RBI-regulated lenders, compare on APR.See how it works
- Top-upA top-up on a loan you haveMore money on an EMI you already pay, priced near your original rate.See how it works
- One EMI loanOne EMI for all your loansLoans and card balances combined into one loan, one rate, one date.See how it works
Finsa is a Lending Service Provider, not a lender. Every offer names the bank or NBFC and carries its Key Fact Statement; the lender decides, prices and pays into your account.
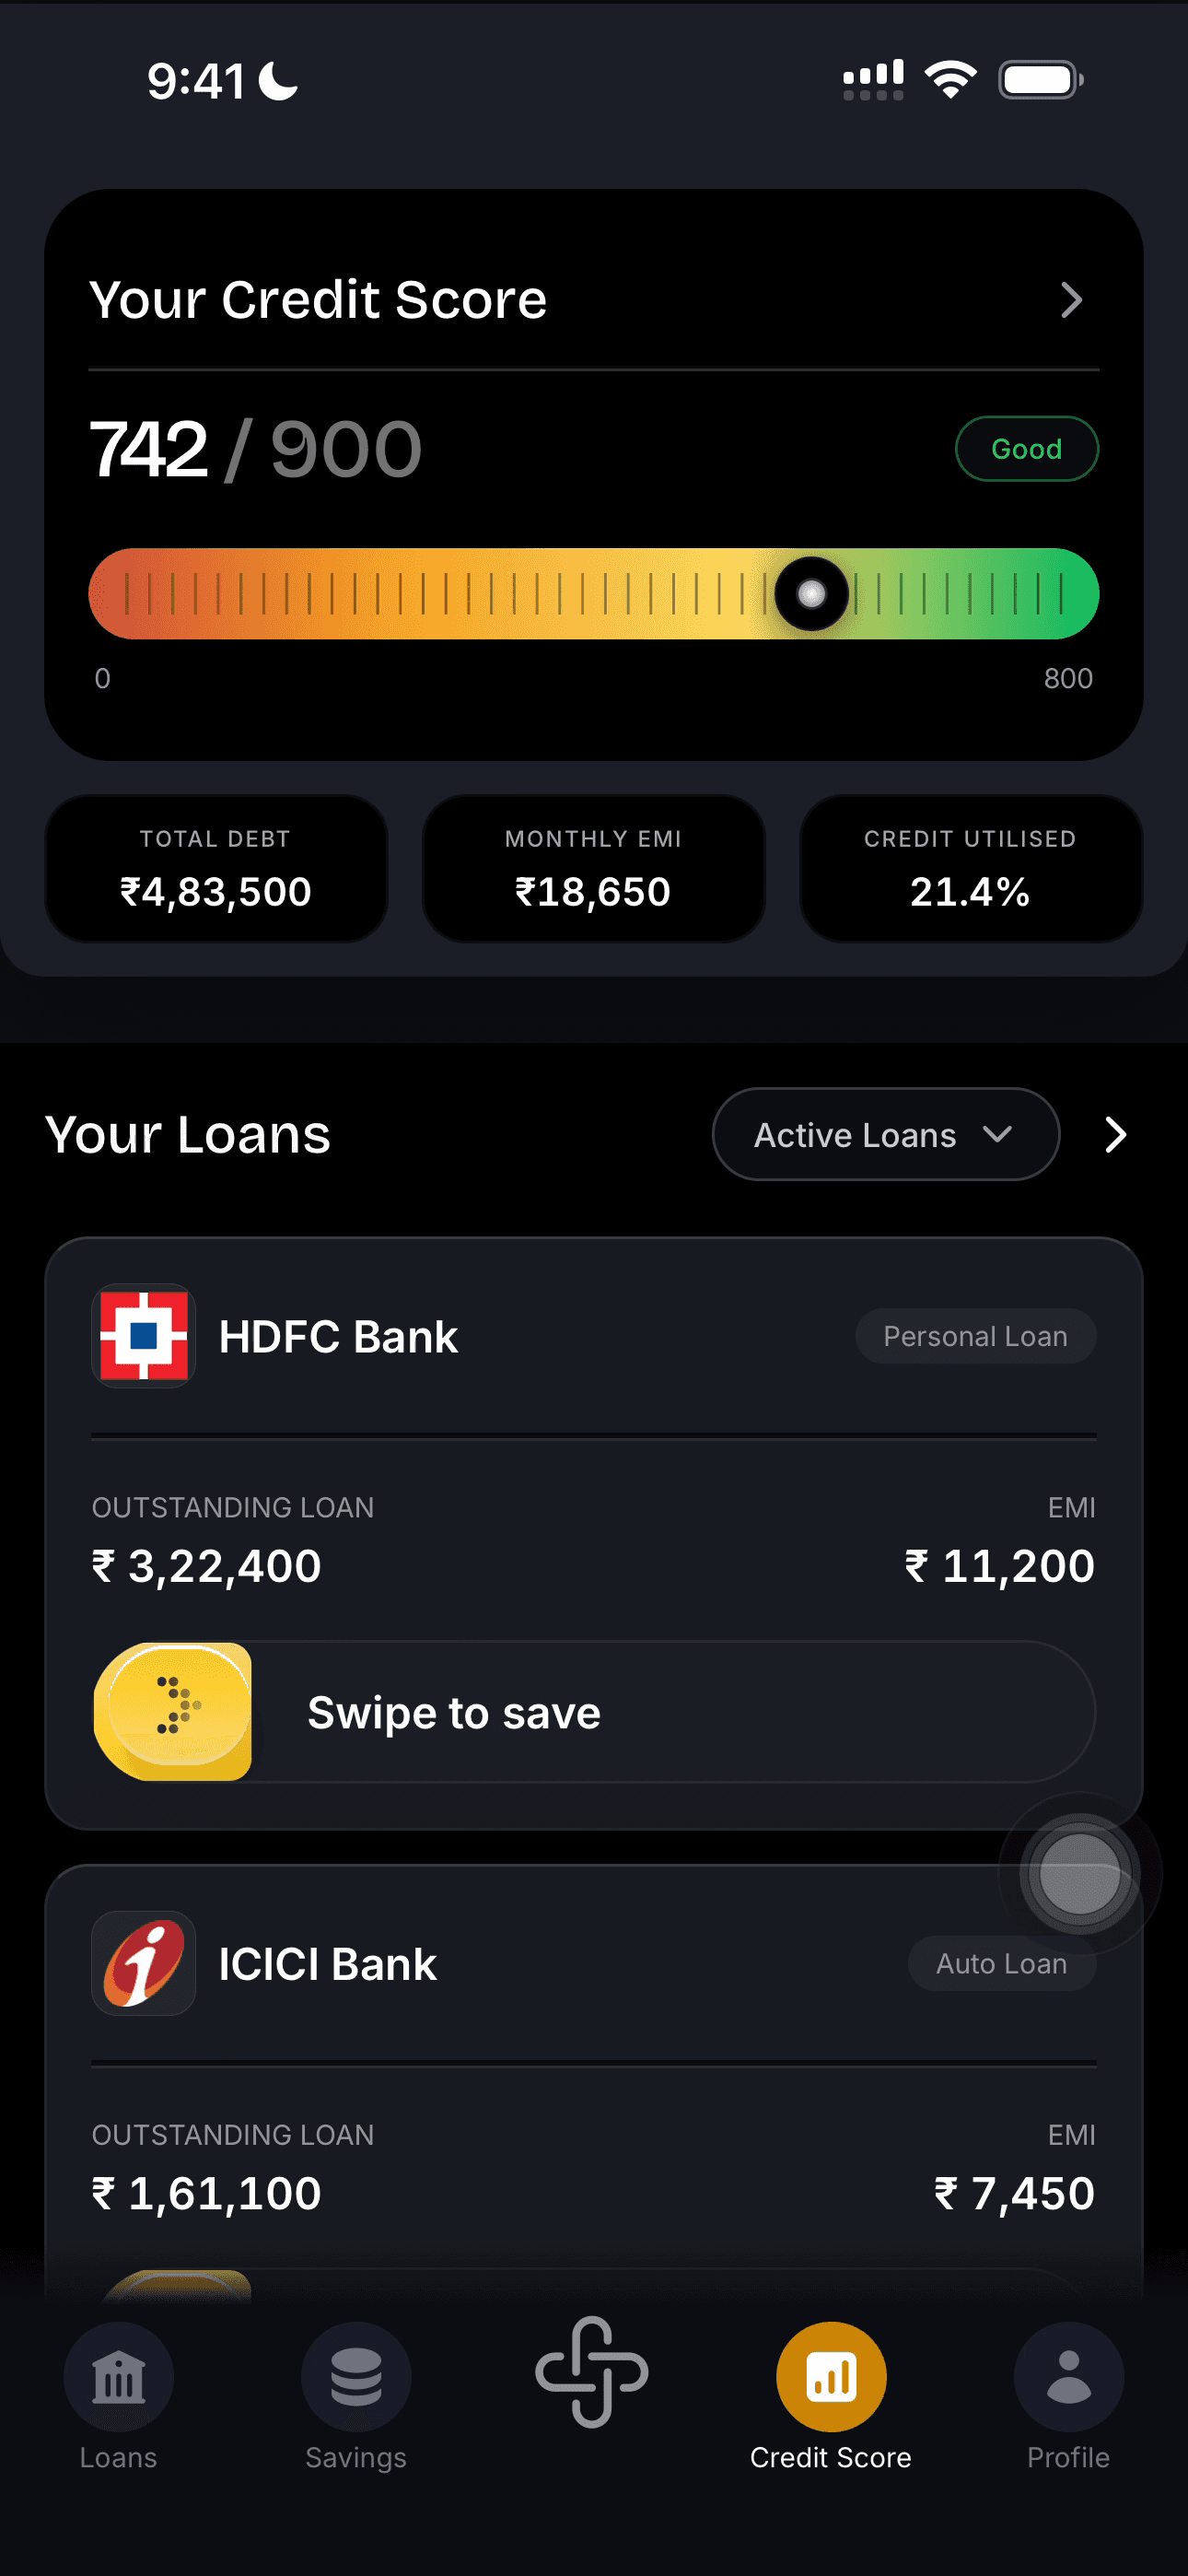
See every loan — and its rate.
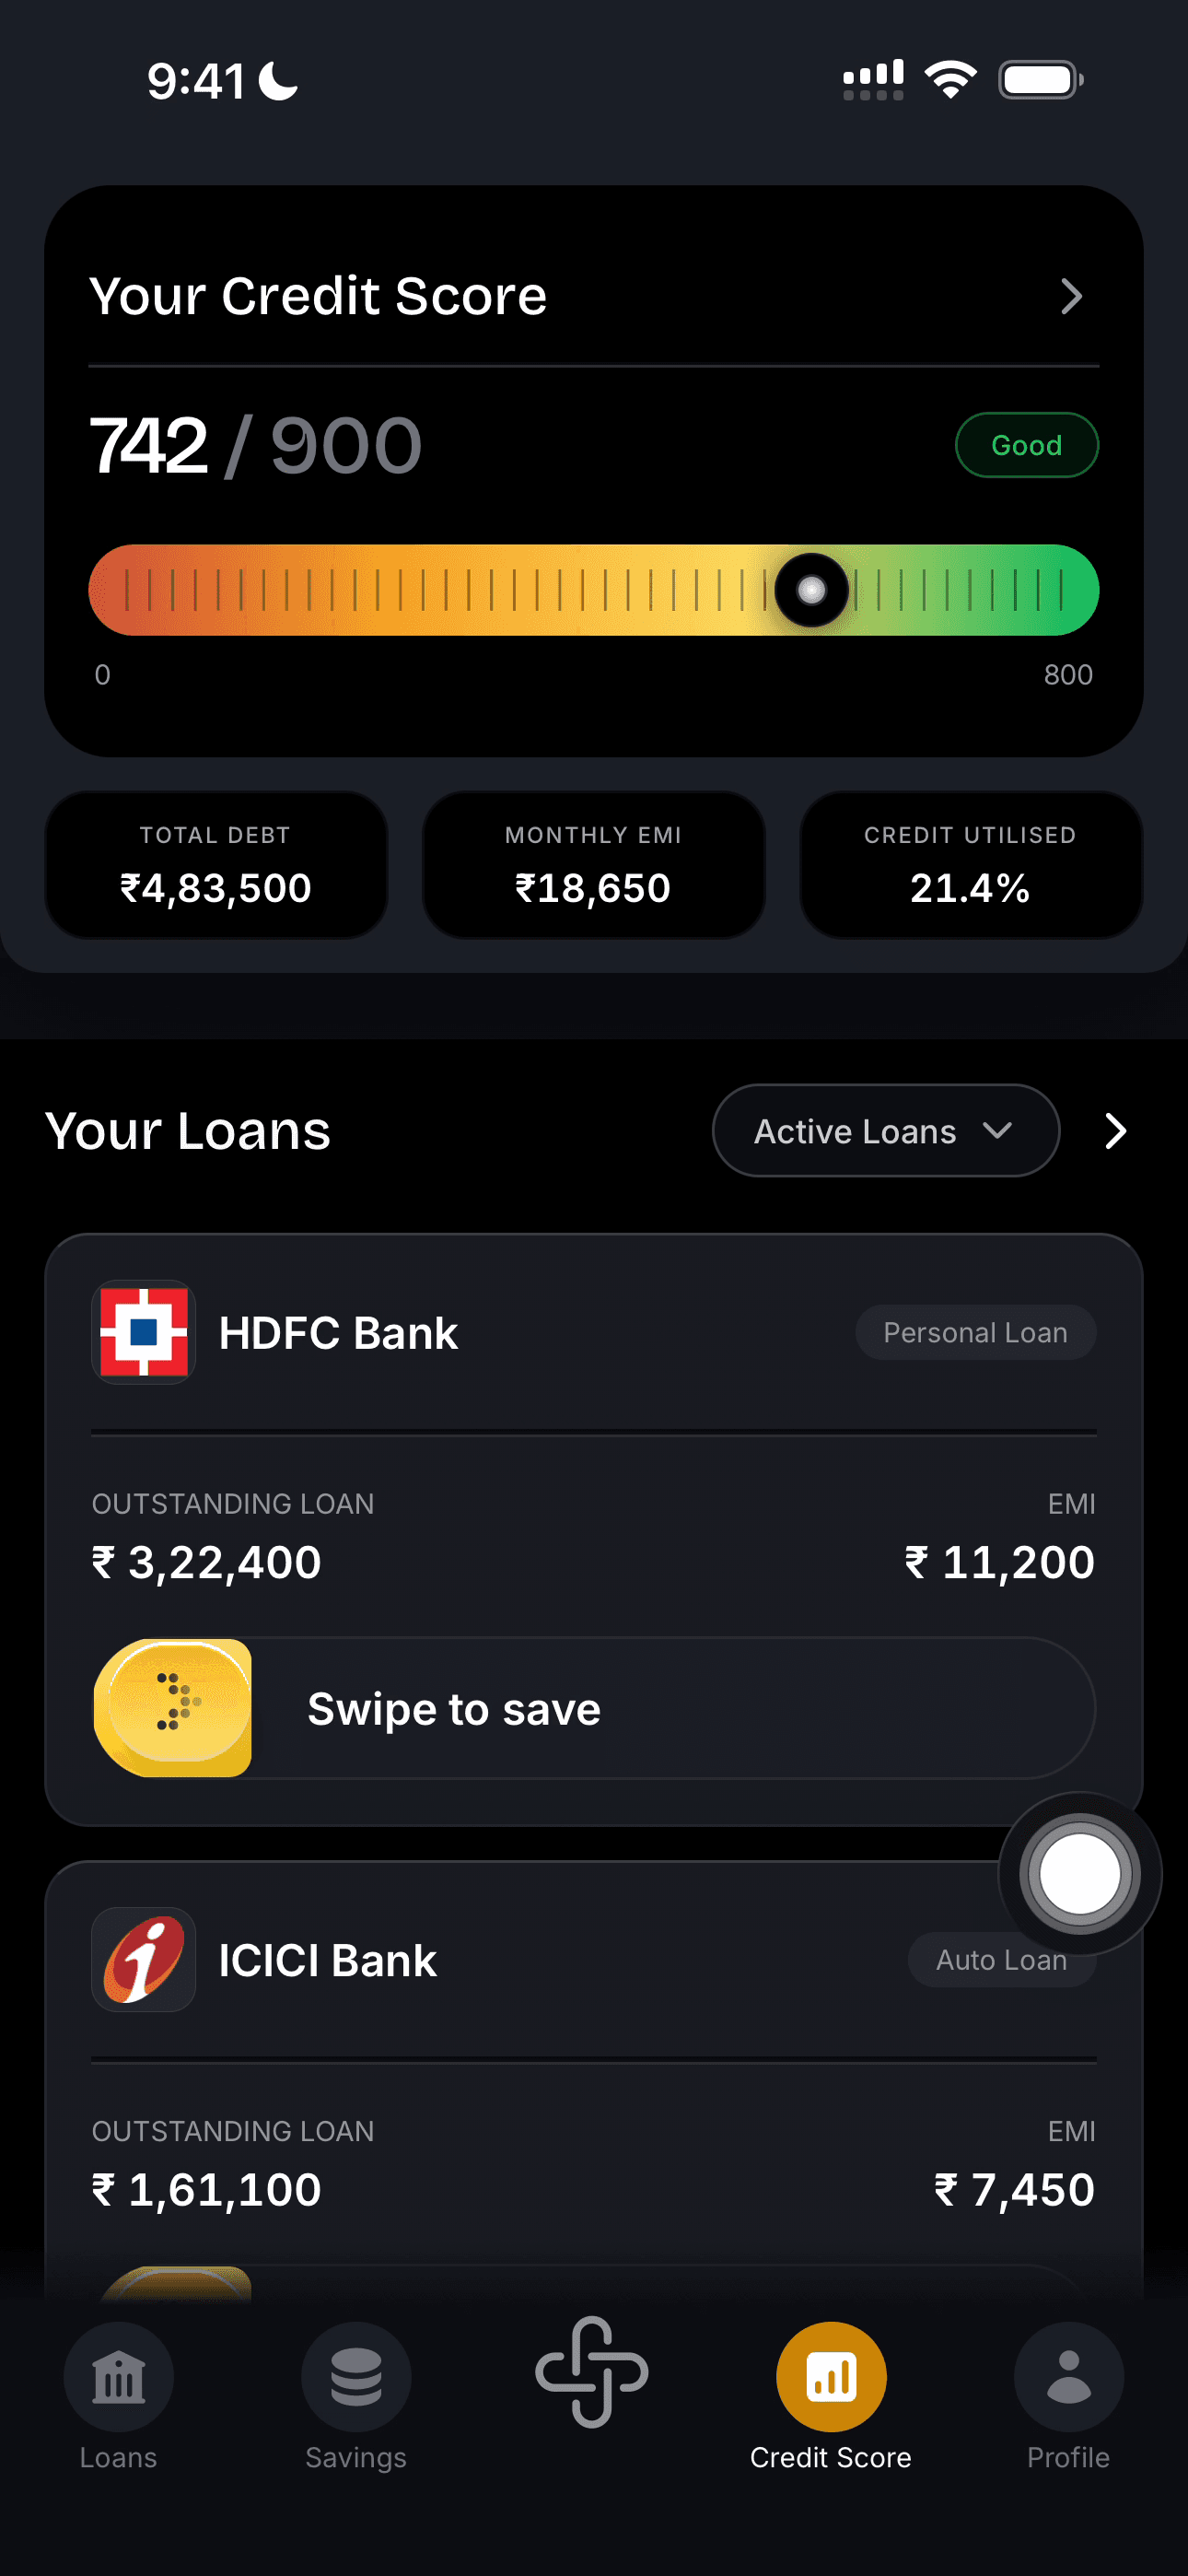
Outstanding, EMI and the rate, loan by loan. The expensive one jumps out.
Your loans · from the report
The 13.5% is the one to take to the panel — a balance transfer, if a lender beats it.
Then our lender partners compete.
A soft check that never touches your score. You pick the winning offer.
Sent to our lender partners. The offers are their call — the pick is yours.
The Finsa difference
Every loan gets a gold pot.
Pick the loan. Put ₹100 a day into 24K gold. Finsa keeps that pot pointed at that loan. Then sell it back to your bank, in one tap.
01 · Save
₹100 a day, aimed at one loan.
0.0000 g of 24K, tagged to your HDFC loan
Pick the loan. The HDFC personal loan — ₹3,22,400 outstanding at 13.5%.
Daily, weekly or one-time. ₹100 a day, tagged to that loan's bucket. 24K, held by SafeGold.
Rate locked for 7 minutes. 0.0061 g bought at ₹16,263 a gram. Insured vault, Brinks India.
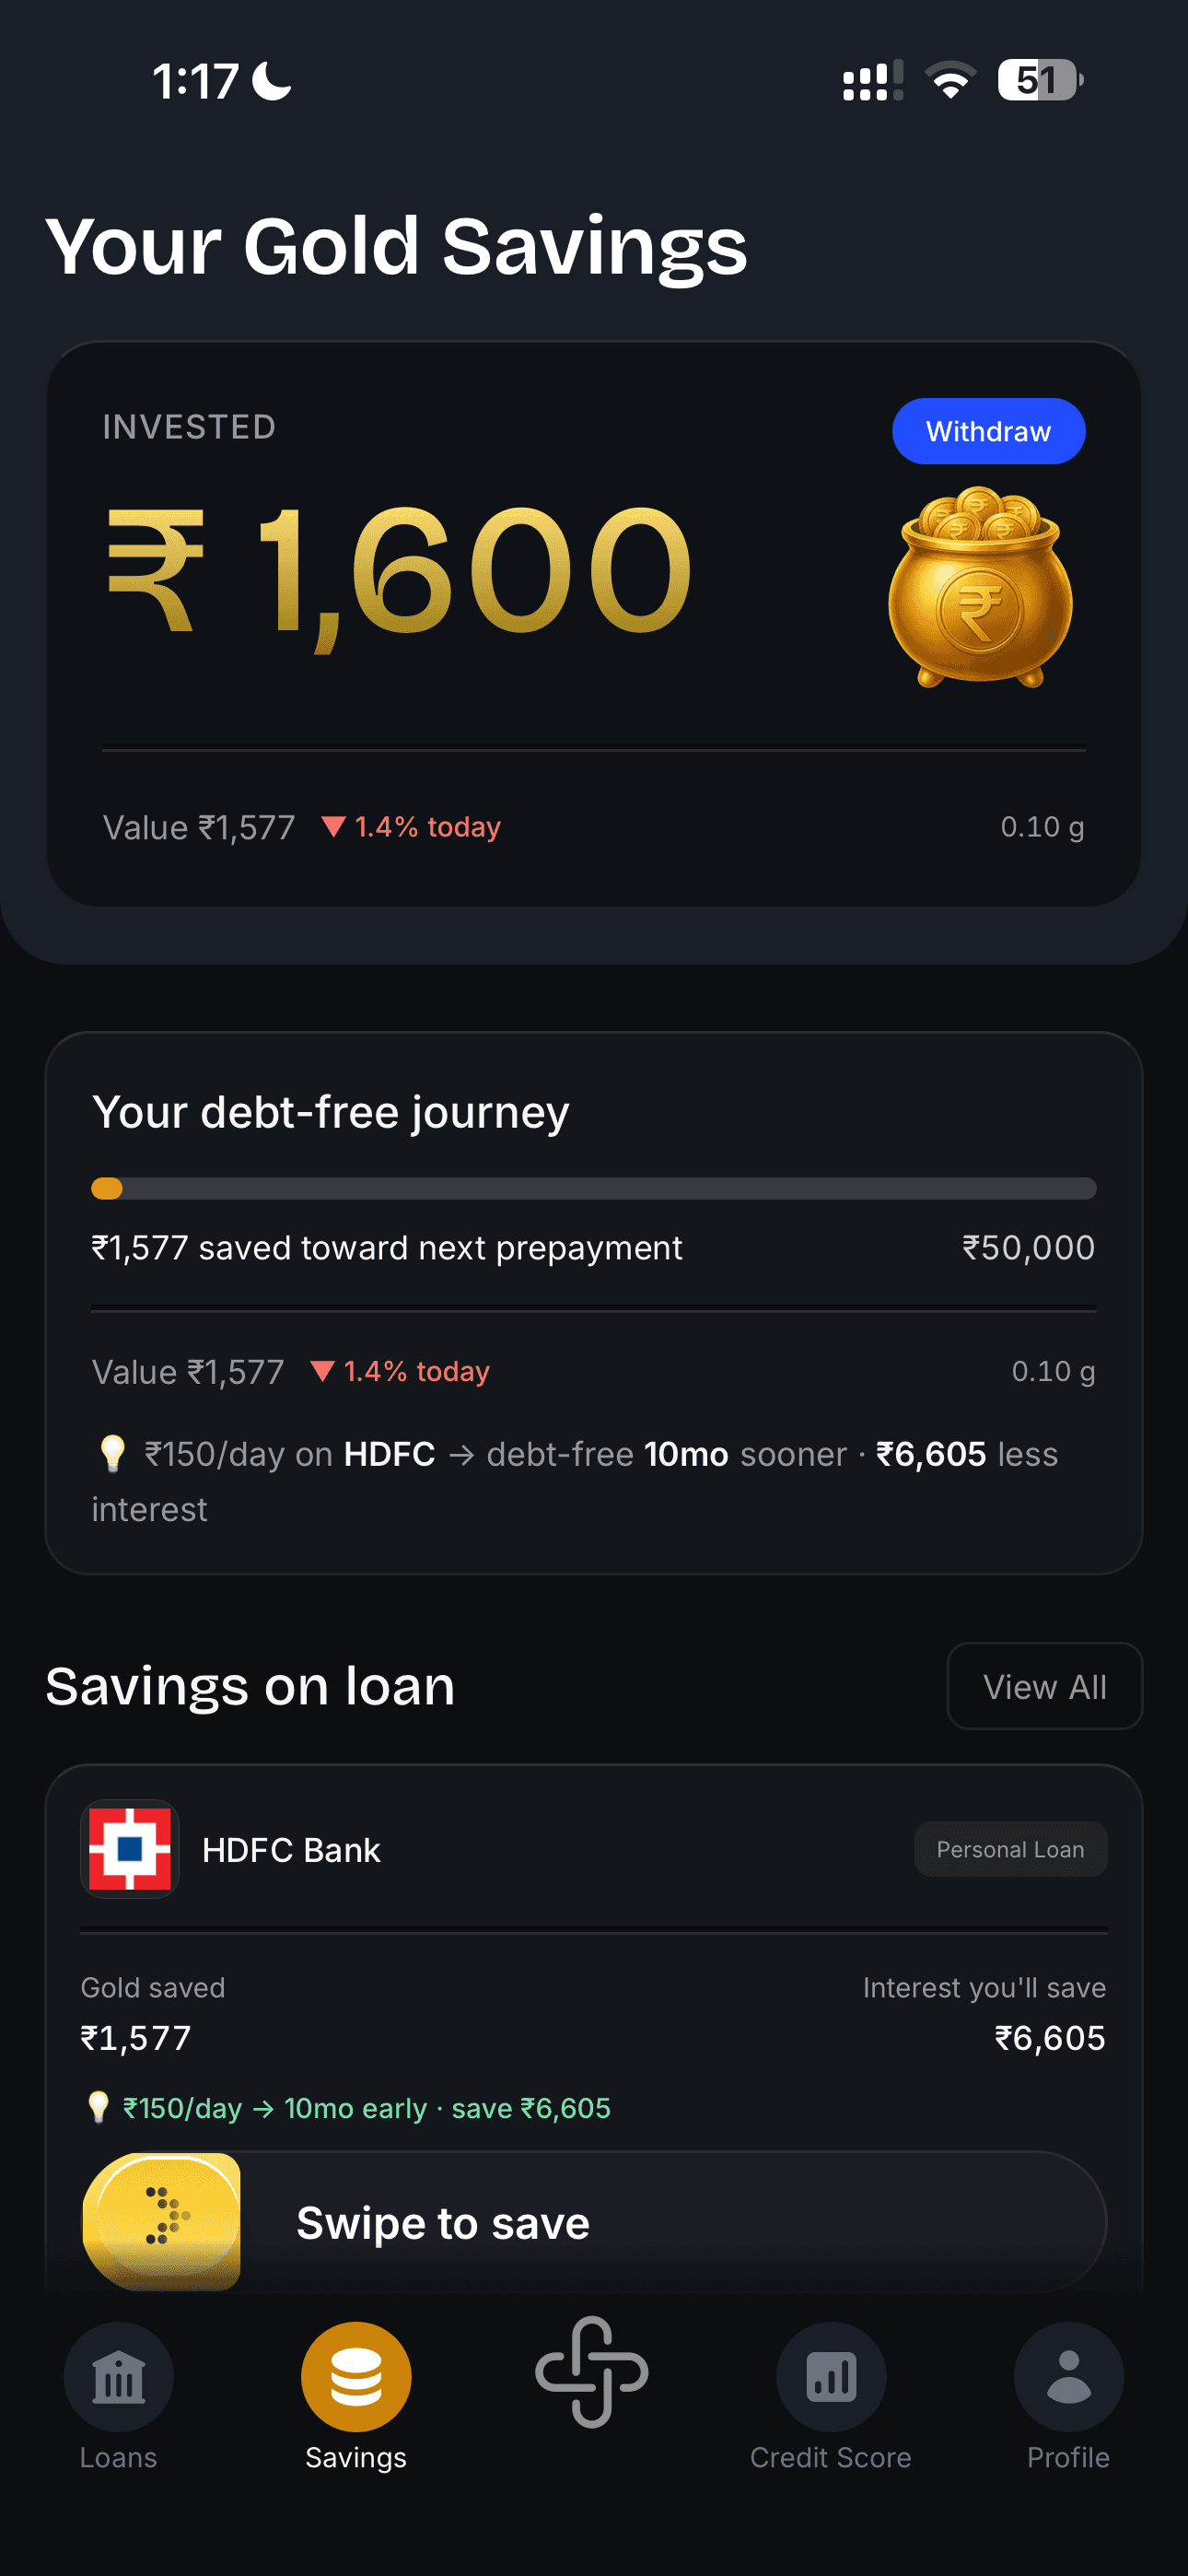
It shows up as a pot. ₹1,600 in, 0.10 g, and a debt-free journey that has started moving.

02 · Sell
Sell it back in one tap.
Any amount, at the live SafeGold sell rate. Tap Withdraw Max and the number is yours.
0.0039 g at ₹15,299.53 a gram. No Finsa fee — what you sell is what you get.
IMPS to your bank, usually within 30 minutes. Real gold, leaving as money.
Gold is market-linked; its value can fall. Prices and 3% GST are passed through without markup. Finsa does not provide investment advice.
Ask Finsa
It has read your credit report. Have you?
Tap a question. The app answers — recorded on the demo account, not typed for the page.
Finding: Room for a new EMI of ₹23,850 a month — about ₹6.98 L over 36 months. 742 is comfortably in lender range.
Indicative, and about the demo account. Finsa is not a lender — eligibility, rate and approval are the lending partner's call.
How it works
You check your report. They send the offers.
Two minutes. Soft check — no hit to your score.
02 · Our lender partners see it at once




03 · Offers come back. You pick.
Rates are revealed when lenders respond — their call, not ours.
Finsa is a Lending Service Provider — not a bank or an NBFC. We do not lend or set rates; every credit decision, interest rate and fee belongs to the lending partner, who provides a Key Fact Statement before you sign. We never take custody of loan funds.
Get the app
Your whole credit life, in one dark room.
Your Equifax score and the six factors moving it, what you may qualify for before you apply anywhere, and a 24K gold pot you can aim at a loan you already have.
Android — available now
A direct download while the Play Store listing is in review. Same build, same signing key, straight from us.
Download for Android66 MB · Android 7.0 and above · free, no account needed. What your phone will ask you.
iPhone — in review
The iOS app is with Apple. Leave your number and we will message you the App Store link the day it clears — we will not use it for anything else.
Tell me when iOS is outFree tools
Run the numbers before you borrow.
No sign-up, no email, no credit check. Just the same reducing-balance maths your lender uses.
Questions
The things people ask before they start
Finsa is a Lending Service Provider. We don't lend — our RBI-regulated partners do.
No. Finsa is not a bank or an NBFC and does not lend money. It is a matchmaker: it reads your credit report and puts your profile in front of RBI-regulated banks and NBFCs so they compete for it. Every credit decision, interest rate and fee belongs to the lending partner, who gives you a Key Fact Statement before you sign anything.
No. Finsa runs a soft enquiry, which is visible only to you and never affects your score. What can affect it is applying to several lenders directly in a short window — each of those is a hard enquiry. Comparing through Finsa is one soft check instead of many hard ones.
Yes, and there is no subscription or in-app purchase. Finsa is paid a commission by the lender when a loan is disbursed, which is why the borrower is never charged. You are not obliged to take any offer you are shown.
Finsa charges no processing fee and no fee of any kind: the credit report, the offers and the match are free to the borrower. Finsa is paid by the lender on disbursal. Any processing fee of the lender's own is shown on its Key Fact Statement before you sign, and you can compare offers on that.
Equifax. You get the same 300–900 score lenders see, refreshable once a month, along with the six weighted factors moving it: payment history, credit utilisation, EMI burden, recent enquiries, credit age and mix, and any overdue accounts.
A balance transfer moves an existing loan to a lender charging less. It is worth doing when the rate difference outweighs the new lender's processing fee and any foreclosure charge on the old loan — usually when you are more than one or two percentage points above what your profile can get today, and you still have a reasonable tenure left to save over.
Your name, mobile number and an OTP you verify yourself. Nothing is fetched until you give explicit consent in the app. Your data is stored in India, and you can withdraw consent or delete your account and everything in it from inside the app.
Plain answers
The questions people ask before they borrow, answered in two sentences each.
- Can I get a personal loan with a 700 credit score?
- How much personal loan can I get on my salary?
- Is a personal loan balance transfer worth it?
- Should I consolidate my loans into one?
- Top-up loan or a new personal loan — which is better?
- Does checking my credit score lower it?
- How do I close a personal loan early?
- What is a Key Fact Statement, and what should I check in it?
- Why is my Equifax score different from my CIBIL score?
- What is a Lending Service Provider, and is it safe to use one?
- Can I get a personal loan with no credit history?
- Does a personal loan balance transfer hurt my credit score?
- Can I get a personal loan without a processing fee?
- Can my EMI be reduced?
- What happens if I miss an EMI, and what should I do?
- Is there a CIBIL defaulter list, and can a defaulter get a loan?
- What is a loan settlement, and how is it different from closing a loan?
- What is the difference between a flat interest rate and a reducing interest rate?
- Does a no-cost EMI affect my credit score?
- What documents do I need for a personal loan?
- What decides the interest rate on my personal loan?
- Can I really get an instant personal loan online?
- How do I get a top-up on my existing personal loan?
- Is a pre-approved personal loan offer worth taking?
- Which personal loan app is safe to use in India?
- Can I get a personal loan with a low CIBIL score?
- How does a self-employed person get a personal loan?
- Which phone app is best to take a personal loan in India?
- Where can I get a personal loan in India?
- Can saving in gold help me close my loan early?
Your better rate is one form away.
Two minutes, a soft check that won’t touch your score. We put you in front of our lending partners and call you with their offers — you decide.
- 01
Tell us what you need
Amount, purpose, a few basics. Under two minutes on WhatsApp or the form — and checking never touches your credit score.
- 02
Every lender answers at once
We run your profile against RBI-regulated banks & NBFCs simultaneously and bring back what each one will actually do.
- 03
Money in your account
You choose. The lender disburses directly to your bank account — Finsa never touches your funds.
- Soft check only
- Free for you
- Data stays in India
Finsa is a Lending Service Provider. We don't lend — our RBI-regulated partners do.